
A monthly budget is a short plan that matches the money coming in each month with the money going out, written down before the month starts. It does not need an app or a spreadsheet. A notebook works fine, as long as the numbers are real and the plan gets a quick look every week.
Table of Contents6 sections
This guide covers one simple way to build a first budget, compares the most common methods and explains what usually goes wrong in the second month.
What Is a Monthly Budget?
A monthly budget is a list of expected income and planned spending for one month, where planned spending is equal to or lower than income. The point is to decide in advance where money goes, instead of finding out at the end of the month.
Most budgets have three basic parts. Income is take-home pay after tax and other deductions. Fixed costs stay roughly the same each month, such as rent and a phone plan. Variable costs move up and down, such as groceries, fuel and eating out.
A fourth line for saving or a planned purchase turns the budget from a record of the past into a plan for the month ahead.
How Do You Make a Monthly Budget Step by Step?
You make a monthly budget by working out take-home pay, listing every regular cost and then giving whatever is left a specific job. The five steps below take about an hour the first time and much less after that.
Step 1: Write down your take-home pay
Start with the amount that actually lands in the bank account, not the salary on a contract. For weekly or fortnightly pay, add up the payments that arrive within one month.
People with uneven income, such as freelancers or shift workers, often build the budget around their lowest month from the past year. That way the plan still holds in a slow month, and a good month becomes a bonus.
Step 2: List your fixed costs
Fixed costs are bills that arrive for about the same amount on a regular date. Rent, utilities on a fixed plan, phone and internet, childcare and travel passes usually belong here. Recent bank statements are the quickest way to find them all.
Step 3: Estimate variable spending from real statements
Variable costs are where most first budgets go wrong, because memory tends to underestimate them. Go back over the last two or three months of bank and card statements and add up groceries, fuel, takeaways, clothes and small purchases.
Use the monthly average as the starting figure. The goal at this stage is an honest number, not the number that would look nice.
Step 4: Turn irregular costs into monthly amounts
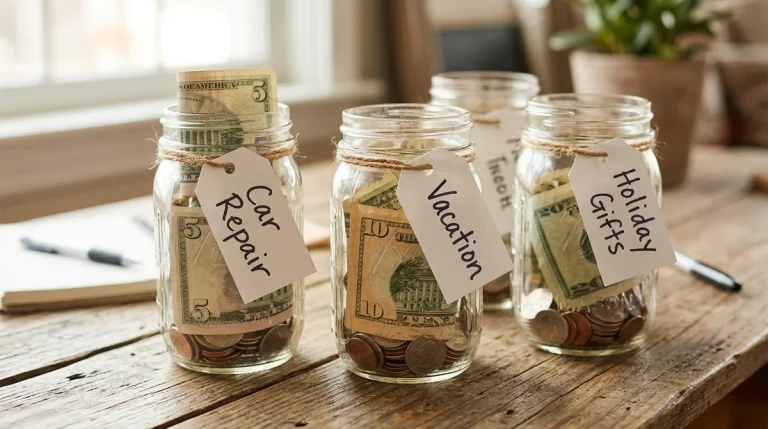
Some costs arrive only once or twice a year, such as a car service, a yearly membership or school uniforms. Divide each yearly amount by 12 and add that figure to the monthly plan.
This one step stops a single large bill from wrecking an otherwise good month.
Step 5: Give the leftover a job
Subtract all costs from take-home pay and look at what remains. If there is money left, assign it to something specific, such as a saving goal or a planned purchase, so it does not drift quietly into everyday spending.
If the result is negative, the variable costs from Step 3 are usually the first place to look, since fixed bills are harder to change quickly.
Which Budgeting Method Fits Which Person?
The 50/30/20 rule suits people who want one simple starting rule, zero-based budgeting suits people who like detail, the envelope method suits people who overspend on food or going out, and pay yourself first suits people who dislike logging every purchase. No single method is right for everyone, and the table compares the four approaches in plain terms.
| Method | How it works | Often suits |
|---|---|---|
| 50/30/20 | About 50% of take-home pay goes to needs, 30% to wants and 20% to saving or paying down money owed | People who want one simple starting rule |
| Zero-based | Every unit of income gets a job until income minus planned spending equals zero | People who like detail and control |
| Envelope | Set amounts go into separate envelopes or app pots for each category, and spending in a category stops when its pot is empty | People who tend to overspend on food or going out |
| Pay yourself first | A saving amount moves out on payday and the rest is spent with less tracking | People who dislike logging every purchase |
The 50/30/20 split was made popular by Elizabeth Warren and her daughter Amelia Warren Tyagi in their book All Your Worth. Many households treat the percentages as a starting point and adjust them, since rent alone can take more than half of take-home pay in expensive cities.
Mixing methods is common too. Someone might use 50/30/20 for the big picture and envelopes for the one category that keeps running over.
How Do You Stick to a Budget After the First Month?
A budget lasts when it gets checked often and changed when life changes. A short weekly look at spending, about ten minutes, catches problems while there is still time left in the month to adjust.
- Pick one day a week to compare real spending against the plan.
- Move money between categories when one line runs over, rather than dropping the whole budget.
- Keep a small “miscellaneous” line for the costs nobody predicts, such as a birthday gift or a parking fine.
- Review the whole plan when income, rent or household size changes.
- Round estimates up, not down, for the first three months.
A budget that is roughly right and checked every week usually works better than a perfect one nobody looks at.
What Are the Most Common Budget Mistakes?
The most common mistake is building a budget around hoped-for spending instead of real numbers. Using actual statements in Step 3 fixes most of that.
Forgetting yearly costs comes a close second, which is why Step 4 matters. Leaving zero room for small treats also tends to backfire, because a plan with no fun money at all often breaks within a few weeks.
A month that runs over budget still teaches something useful. It shows which category needs a more honest number next time.
FAQ
What is the 50/30/20 rule?
The 50/30/20 rule splits take-home pay into about 50% for needs, 30% for wants and 20% for saving. It works as a guideline, and many people adjust the split to fit local living costs.
What if expenses are higher than income?
When planned costs add up to more than take-home pay, people usually start by looking again at variable spending and subscriptions, since those are quicker to change than rent or utilities. If a gap remains after that, a free non-profit money advice service in your country can look at the full picture.
How often does a budget need updating?
A short weekly check and a fuller review once a month is a common rhythm. Any change in income or rent is a good moment for a complete rewrite.